If you owe the IRS more than you can realistically pay, an Offer in Compromise lets you settle for less than the full balance, but only if your numbers support it. The calculator above runs the same math the IRS uses internally: quick-sale value on your assets, disposable income, and a payment-length multiplier, so you get a real number in under a minute instead of a guess.
Enter your tax debt, income, expenses, and assets, and see roughly where you stand before you commit hours to paperwork or a call with a tax professional.
How This IRS Offer in Compromise Calculator Works
The tool is built around three short steps and one formula behind the scenes.
- Eligibility check: three quick yes/no questions on filing compliance, open bankruptcy, and estimated tax payments. The IRS won't review an offer from someone who hasn't filed every required return, regardless of how the rest of the numbers look.
- Financial snapshot: your total tax debt, monthly income, and monthly necessary expenses, which the calculator nets out to your disposable income.
- Assets and payment option: what you own, any secured debt against it, and whether you'd pay as a lump sum or over up to 24 months.
Behind those inputs, the calculator adds two numbers together: your net realizable equity (roughly 80% of what your assets would sell for, minus secured debt) and your future income (disposable income multiplied by 12 or 24 months, depending on your payment choice).
If you're not sure exactly what you owe, it's worth taking a minute to find out how much you owe the IRS first, so the result isn't built on a guess.
A low number here doesn't guarantee the IRS will accept it. Plenty of taxpayers fall for common Offer in Compromise myths, like assuming a settlement is available just because they ask for one, so treat the result as a planning tool, not a guarantee.
Who Actually Qualifies for an Offer in Compromise
This calculator estimates what's called a doubt as to collectibility offer, the most common type, built around whether you can realistically pay your full balance before the collection window closes. Two other paths exist that this tool doesn't estimate:
- Doubt as to Liability: For taxpayers who believe the assessed tax itself is wrong, not just unaffordable.
- Effective Tax Administration: For taxpayers who could technically pay in full, but doing so would create genuine economic hardship or an unfair result.
Beyond picking the right category, baseline eligibility is strict: every required return needs to be filed, you can't be in an open bankruptcy case, and you need to be current on any required estimated tax payments. Missing any one of those generally stops an offer before the financial review even starts.
If you're weighing whether an OIC is the right move at all, signs you should apply for an OIC cover the situations where it tends to make the most sense.
How the IRS Actually Determines What You Can Pay
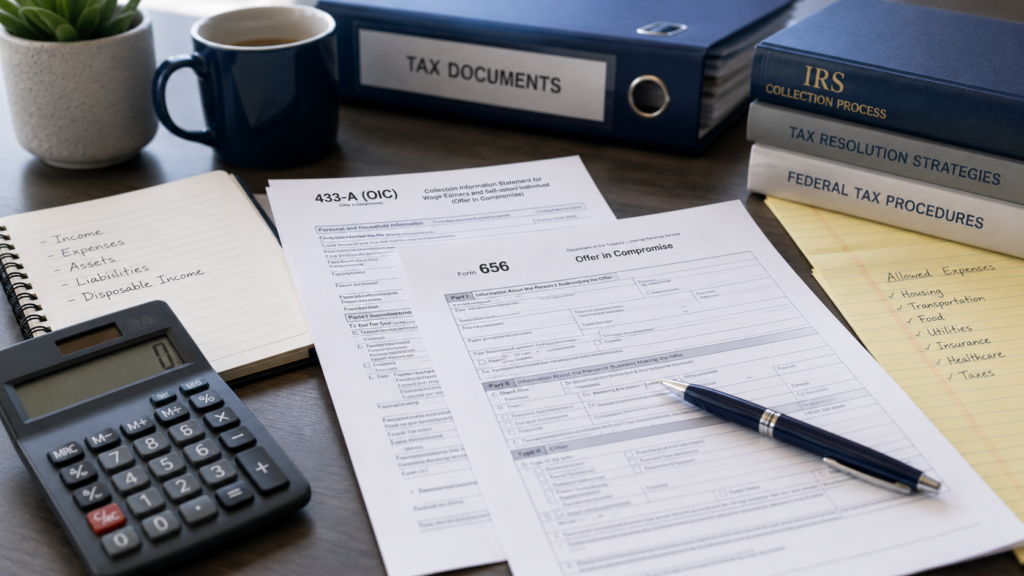
The IRS calls this number your Reasonable Collection Potential, or RCP, and it's built from two pieces.
- Net realizable equity: what your assets would sell for in a hurry, roughly 80% of fair market value, minus whatever you still owe against them.
- Future income: your monthly income minus necessary living expenses, multiplied by 12 months for a lump sum or 24 months for a periodic plan.
The IRS caps what counts as a "necessary" expense using its own published standards for things like housing, transportation, and food, rather than whatever you actually spend. That's a common source of confusion; your real budget and the IRS's allowed budget aren't always the same number.
Full documentation of this analysis happens on Form 433-A (OIC), and the formal offer itself gets submitted on Form 656. Both ask for far more detail than any calculator can, right down to vehicle mileage and retirement account balances.
What Happens After You Submit an Offer
Getting a number is one step; filing the actual offer is another. A few things worth knowing going in:
- A nonrefundable deposit is required with your application: 20% of the offer amount for a lump sum, or your first proposed installment for a periodic plan, paid whether or not the offer gets accepted. A separate $205 application fee also applies, waived only for taxpayers who meet the IRS's low-income guidelines.
- Review takes time: the IRS investigates your full financial picture before deciding, so offers aren't approved or denied overnight.
- Not every well-calculated offer gets accepted. According to the appeal process for a rejected Offer in Compromise, the IRS usually rejects offers because it believes the amount is too low, that you can pay more than you offered, or that the living expenses used in the calculation were too high, not necessarily a flaw in the math itself. A rejection isn't final either; you generally have 30 days to appeal using Form 13711.
- If your RCP comes out at or above your balance, an OIC likely won't help. Currently Not Collectible status or an IRS installment agreement tend to fit that situation better.
Whether you think of it as a tax offer estimate or a compromise calculator for your total balance, the number you land on is only a starting point for that process, not the end of it.
Turn This Estimate Into Real Leverage
Most people who owe the IRS either overpay out of fear or send in a lowball offer that gets rejected outright. The ones who come out ahead almost always know their real number before they file anything.
Run the calculator, see where your estimate lands, and use that to decide what's next. That might mean moving forward with an Offer in Compromise, or it might mean Currently Not Collectible status or an installment agreement makes more sense instead.
Partner with The W Tax Group to turn that estimate into an actual filed offer.
Frequently Asked Questions
How does an Offer in Compromise calculator work?
It applies the IRS's Reasonable Collection Potential formula (quick-sale value of your assets plus future disposable income) to the numbers you enter, giving you an estimate of what the IRS might accept.
How does the IRS calculate an Offer in Compromise?
The IRS adds the quick-sale value of your assets, minus secured debt, to your monthly disposable income multiplied by 12 or 24 months, depending on your payment structure. Allowable expenses are capped by IRS standards, not your actual spending.
How much should I offer the IRS in an Offer in Compromise?
At minimum, enough to meet your Reasonable Collection Potential. Offering less almost always gets rejected, while offering significantly more gives away money you didn't need to.
Does an Offer in Compromise calculator tell me if I qualify?
No. It estimates a dollar amount based on RCP, but eligibility also depends on filing compliance, bankruptcy status, and current estimated tax payments, factors the IRS reviews separately from the math.
Can a tax attorney help me apply for an Offer in Compromise?
Yes. An Offer in Compromise attorney can value your assets correctly, document your expenses in a way the IRS accepts, and push back if an examiner's numbers don't match your actual situation, all of which affect whether an offer gets approved.