A late return doesn’t just sit there quietly. Every month it stays unfiled, the cost behind it keeps growing, and most people don’t find out how much until a notice shows up months later.
This IRS late filing penalty calculator puts that number in front of you now, using the same math the IRS runs behind the scenes, before a letter ever does it for you.
Whether you’re still deciding how fast to file or already holding a bill you don’t fully understand, having a real number changes what happens next.
What Goes Into the Estimate
Four pieces of information drive the result, and each one moves the number in a specific direction:
- Unpaid tax at the original deadline: What remained owed after withholding, estimated payments, and any credits, not a current balance that may already include added penalties or interest
- Tax year the return was for: Selecting the year applies that year’s actual IRS filing deadline automatically, including years the date shifted off April 15 for a weekend or a D.C. holiday, so there’s no risk of typing in the wrong date
- Extension status: Answering yes applies that year’s October deadline as the starting point the penalty clock runs from, with no separate date to look up or enter
- Date filed: the month, day, and year the return was actually submitted, separate from whenever the balance itself got paid
This is the same late tax filing penalty math the IRS applies, not a simplified stand-in for it. Once calculated, the result shows the effective deadline used, the number of penalty months counted, the rate applied, and the dollar estimate. That figure is the failure-to-file penalty only, it does not include the failure-to-pay penalty or IRS interest, both of which are charged separately.
The calculator assumes the unpaid balance sat untouched between the original deadline and the filing date, since that’s the typical scenario, and it’s built specifically around individual Form 1040 returns rather than business filings, which follow separate rules entirely.
It’s worth running the numbers more than once if a return hasn’t been filed yet. Moving the filing date forward by even a single week can shift the estimate by a full penalty month, so testing a couple of dates side by side shows exactly how much waiting costs in dollar terms rather than as an abstract warning.
The Formula Behind the Number
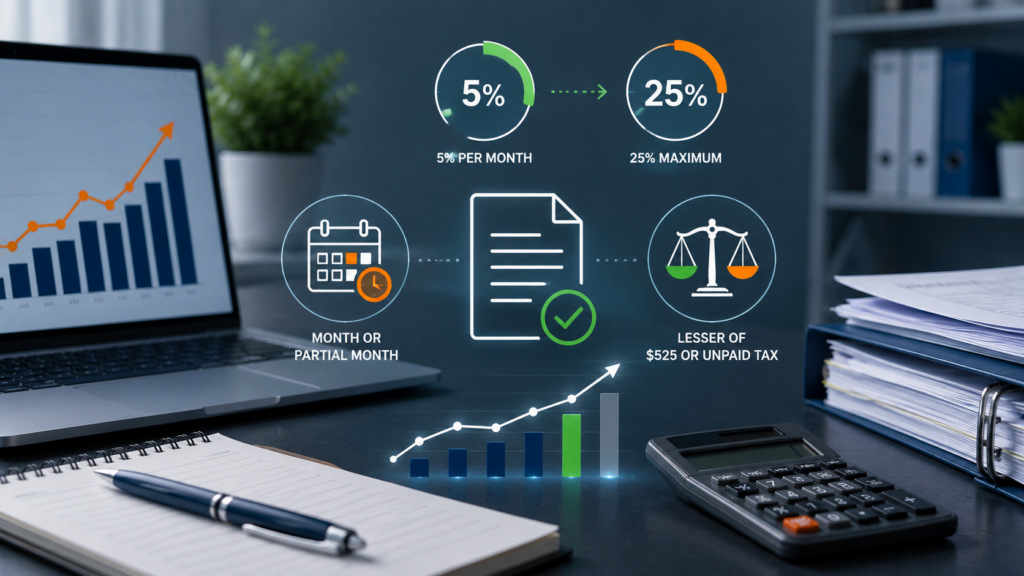
The Failure to File Penalty runs at 5% of the unpaid tax for every month or partial month a return sits late, up to a 25% ceiling.
But when tax is still unpaid at the same time, the IRS trims that rate to 4.5% for the overlapping months, since the other 0.5 percentage point is already being charged separately as a late-payment penalty, and that reduced rate is what this calculator applies whenever a balance is entered. Three details explain most of the confusion around it:
- A single extra day still counts as a full month: File on day 31 instead of day 30, and the penalty jumps by a whole additional month, not a fraction of one.
- An extension only moves the filing deadline: Submitting Form 4868 pushes the paperwork due date to October, but any tax that stayed unpaid since April was never protected by that extension, and a separate penalty tracks it the entire time.
- Sixty days late changes the math entirely: Returns filed more than 60 days after the deadline face a floor penalty, the lesser of $525 or the full unpaid balance for returns due in 2026, that takes over whenever it’s larger than what the percentage-based math alone would produce.
Worked example: $12,000 unpaid, three months late, no extension. That’s $12,000 × 4.5% × 3, landing at $1,620. That’s the exact math built into the calculator above, not a rounded stand-in for it.
Push that same balance past the five-month mark and the rate stops climbing at its 22.5% ceiling for the filing-penalty side, settling at $2,700 no matter how much additional time passes, though a separate late-payment penalty can continue accruing beyond that point.
Filing Late Costs More Than Paying Late
The two penalties get lumped together constantly, and treating them as one number leads to bad math. Failure to Pay charges 0.5% per month on tax that’s owed but unpaid, a tenth of the rate this tool estimates.
| Failure to File | Failure to Pay | |
| Monthly rate | 5% | 0.5% |
| Cap | 25% of unpaid tax | 25% of unpaid tax |
| Clock starts | Filing due date, or the extended date with a valid extension | Original payment due date, unaffected by any extension |
| What causes it | Return submitted late or never filed | Balance owed but not paid |
When both charges apply during the same month, the IRS trims the filing-penalty side so the combined total holds at 5%, not 5.5%. Think of this as a late filing penalty check running on IRS figures, with a separate calculator handling the payment side, since blending the two into one estimate would misstate both.
For the payment-side number, the IRS late payment penalty calculator applies that 0.5% math, and the IRS installment agreement interest rate page shows what interest layers on top of either penalty.
Lower or Erase This Penalty Before It Grows
A few moves shift this penalty before it grows further, or stop it from applying at all:
- Submit the return even without full payment: Since the filing penalty runs ten times steeper than the payment penalty, getting the paperwork in on time and addressing the balance afterward is nearly always cheaper overall.
- Don’t wait once a deadline has passed: Each month past a missed deadline adds another full 5% until the 25% ceiling is reached, so delay has a direct, calculable cost.
- Look into automatic relief first: As of summer 2026, the IRS’s new Automatic Exemption from Penalty removes this charge with no request required, for taxpayers with a clean three-year filing history on 2025 tax-year returns and later.
- Request relief on reasonable cause grounds: When automatic relief isn’t available, penalty abatement for documented circumstances like illness or a natural disaster, submitted through Form 843, remains worth pursuing.
- Keep a copy of whatever evidence supports the claim: Hospital records, insurance paperwork, or a disaster declaration all strengthen a reasonable cause request, and gathering that documentation early saves time if the IRS asks follow-up questions later.
None of these variables factor into the calculator’s four fields, which is exactly why they’re worth reviewing once an estimate is in hand.
Know the Real Cost Before You Owe More
Most people learn their penalty from a notice months after it stopped accumulating, with no chance to plan around it beforehand. Working the math out first removes that surprise entirely.
Start with the calculator above, then find out how much you owe the IRS across every open year if more than one return is involved. When the balance is more than you can pay outright, The W Tax Group can help map out a payment plan before additional penalties stack on top.
Frequently Asked Questions
How does the IRS late filing penalty calculator work?
It takes your unpaid tax amount, the tax year the return was for, whether you filed an extension, and the date you filed, then applies that year’s correct IRS filing deadline automatically, counts penalty months by calendar date rather than a flat 30-day average, applies the 4.5% overlap rate that covers the typical case where tax is also unpaid, and factors in the 60-day minimum where it applies.
How does the IRS calculate the late filing penalty?
Five percent of the unpaid tax gets charged for each month or partial month a return remains late, capped at 25%. Past 60 days late, a floor penalty applies whenever it’s larger than that percentage-based math, using whichever amount is smaller between a flat figure set for the filing year and the total unpaid tax.
How long does the IRS charge a late filing penalty?
The percentage-based charge accumulates for a maximum of five months before hitting its 25% cap. Accrual stops once the return is filed or that cap is reached, though a separate late payment penalty and daily interest can continue well beyond that point.
Is there a maximum IRS late filing penalty?
The failure to file penalty tops out at 25% of the unpaid tax. Add in the failure to pay penalty’s own 25% ceiling, and the two combined can reach as much as 47.5% of the original balance under the worst-case timeline.
Does the IRS late filing penalty apply if I don’t owe any taxes?
Usually not. Since the penalty is calculated as a share of unpaid tax, a return showing a zero balance, or one entitled to a refund, generally avoids a failure to file penalty even when it’s submitted after the deadline.
What is the difference between the IRS late filing penalty and late payment penalty?
Filing late triggers a 5% monthly charge on the unpaid tax, while paying late triggers a separate 0.5% monthly charge. In any month where both apply, the IRS caps the combined rate at 5% rather than letting them stack to 5.5%.
Can the IRS waive a late filing penalty?
Yes. Since summer 2026, the IRS’s Automatic Exemption from Penalty removes it without a request for taxpayers with a clean three-year compliance history on 2025 tax-year returns and later; older tax years still need a phone request or Form 843 under the traditional first-time abatement process. Reasonable cause relief also remains available for circumstances like serious illness, disaster, or other situations outside your control.
Can I avoid the IRS late filing penalty by filing for an extension?
Yes, as long as Form 4868 is filed by the original deadline. That extension postpones the filing due date to October and delays the failure-to-file penalty until after that date, though it does nothing for the payment deadline, so a failure-to-pay penalty can still apply to any balance left unpaid.