A penalty from the IRS rarely arrives with an explanation, just a bigger number than the tax itself. The Failure to Pay Penalty is one of the quietest charges on that notice, and it keeps growing for every month a balance sits unpaid.
This IRS penalty and interest calculator gives you that number before the IRS does, so you know exactly what a late payment is costing you and can plan around it instead of guessing.
Whether you’re deciding whether to pay now or wait, or trying to make sense of a balance that’s already grown, seeing the real penalty changes the decision.
How the Calculator Works
The tool runs on four inputs, and each one changes your result directly:
- Unpaid tax amount: the tax that stayed unpaid during the period you’re estimating, not your full IRS balance if that already includes old penalties or interest
- Tax payment due date: the original date your payment was due, which generally isn’t pushed back by an extension you filed to submit your return
- Calculate penalty through: the date you paid the balance, or today’s date if it’s still outstanding
- Situation for the period: whether an approved installment agreement or a levy notice applied for the whole period, since either one changes the monthly rate used
It’s free to use, and it puts your irs penalty and interest picture in front of you before you pick up the phone. Once you hit calculate, you’ll see five numbers: the unpaid tax you entered, the months or partial months counted, the monthly rate used, the estimated penalty, and your unpaid tax plus that penalty combined.
Think of it as an IRS late payment penalty and interest starting point rather than a locked-in figure, change the through date by even a week and you’ll watch the estimate jump a full month’s worth of charges.
How the IRS Calculates the Failure to Pay Penalty
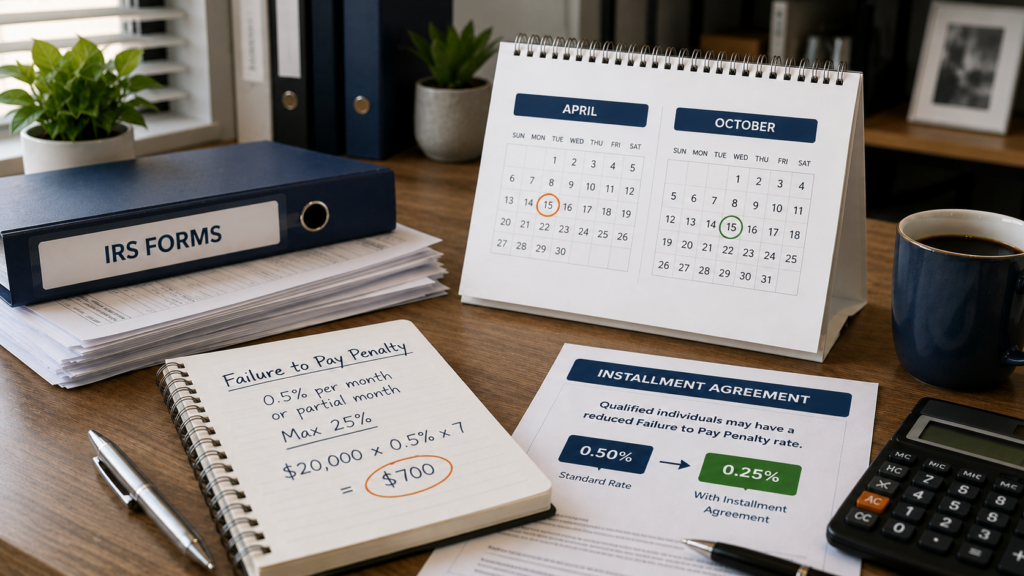
The Failure to Pay Penalty is 0.5% of your unpaid tax for every month or part of a month the balance stays outstanding, capped at 25% of that unpaid tax. Three rules drive most of the confusion:
- Partial months round up. Miss the due date by 32 days instead of 30, and the IRS still counts two full penalty months, not one month and two stray days. It’s a rounding rule that always favors the IRS.
- The clock starts at the payment due date, not the filing deadline. A filing extension buys more time to submit paperwork; it doesn’t push back when the penalty starts accruing. That distinction catches a lot of people off guard: filing Form 4868 in April pushes the paperwork deadline to October, but the Failure to Pay clock has already been running since the original due date the whole time.
- An approved installment agreement can cut the rate in half. Individuals who filed on time with an active IRS payment plan generally see the rate drop from 0.5% to 0.25% per month for the months the agreement is in effect.
Here’s the math on paper: $20,000 in unpaid tax, seven months late, no payment plan, that’s $20,000 × 0.5% × 7, or $700. Running that same irs tax penalty math through the calculator above takes seconds instead of a spreadsheet.
Stretch that same balance out for years without ever paying, and the 25% cap would land at exactly $5,000, no matter how many additional months pass after that point.
Failure to Pay vs. Failure to File, and What Interest Adds on Top
The Failure to Pay Penalty is often confused with the Failure to File Penalty, and the two aren’t interchangeable. Failure to File runs at 5% per month on a return that’s filed late, not just paid late, ten times steeper than the 0.5% rate this calculator estimates.
When both apply in the same month, the IRS reduces the Failure to File portion so the combined charge stays at 5%, not 5.5%, which is exactly why lumping the two into a single number would misrepresent what either one actually costs.
| Failure to Pay Penalty | Failure to File Penalty | IRS Interest | |
| Rate | 0.5% per month (0.25% with an approved installment agreement) | 5% per month | Federal short-term rate + 3%, reset quarterly |
| Maximum charge | 25% of unpaid tax | 25% of unpaid tax | No cap |
| Starts accruing | Original payment due date, never moved by an extension | Return due date, pushed to the extended deadline if you filed a valid extension | Original payment due date, never moved by an extension |
| How it compounds | Flat monthly rate | Flat monthly rate | Daily |
| What triggers it | Tax owed but not paid on time | Return filed late, or not filed | Any unpaid balance, on top of both penalties |
Interest is a separate charge on top of both penalties, and this calculator deliberately leaves it out:
- It compounds daily, not monthly, using a rate set every quarter off the federal short-term rate plus 3 percentage points
- It has no 25% cap, unlike either penalty, so it keeps growing for as long as a balance goes unpaid
- It applies from the original due date, the same starting point as the Failure to Pay Penalty, just calculated on a completely different formula
Keeping IRS interest and penalty figures separate is also why this calculator stays focused on one number instead of guessing at both. For the interest side specifically, the IRS installment agreement interest rate page tracks the current quarter’s figure.
On the same $20,000 balance used earlier, three months of Failure to File would run $3,000 (5% × 3 months) against the $300 this calculator’s 0.5% rate produces for Failure to Pay over that same stretch, a tenfold gap that makes filing on time worth far more than paying on time, even when paying in full isn’t possible yet.
Ways to Reduce or Stop the Penalty From Growing
A handful of situations change the rate or stop the penalty outright; here’s what to check:
- Set up an approved installment agreement. Filing on time and getting a payment plan approved drops the rate from 0.5% to 0.25% per month for every month it’s in effect, cutting future growth in half.
- Watch for a levy notice. If the IRS sends a notice of intent to levy and it goes unpaid for 10 days, the rate can rise to 1% per month instead of dropping. Select that option above, and the calculator applies it directly.
- Check for automatic relief. The IRS’s newer Automatic Exemption from Penalty program grants relief to taxpayers with a clean three-year compliance history without a request, replacing the older first-time penalty abatement process for many returns.
- File for reasonable cause. If automatic relief doesn’t apply, penalty abatement based on reasonable cause, filed through Form 843, is still worth pursuing.
The installment agreement and levy-notice option now cover two of these directly, but the fourth input is still all-or-nothing: it applies one flat rate across the entire period rather than blending rates month by month, so if your situation only applied for part of the stretch, whichever option covers most of it gives the closest simplified estimate.
Automatic relief and reasonable-cause abatement still aren’t reflected in the number at all, since eligibility depends on details the four inputs can’t capture.
See Your Failure to Pay Penalty Before It Grows
Most taxpayers wait for a notice and hope the number isn’t as bad as they fear. The ones who come out ahead usually run their own numbers first, so nothing on that notice is a surprise.
Run the IRS penalty calculator above, see where your estimate lands, and use that to decide what’s next.
Situations beyond four inputs, like several unpaid tax years or a case already assigned to a revenue officer, need a closer look than any calculator can give. Find out how much you owe the IRS first, then let The W Tax Group help you decide what to do about it.
Frequently Asked Questions
How does the IRS late payment penalty calculator work?
You enter your unpaid tax, the original due date, the date you paid (or today’s date if it’s still owed), and whether an installment agreement or a levy notice applied for the period. The tool counts penalty months, applies the correct monthly rate, and caps the result at 25% of the unpaid tax.
How does the IRS calculate late payment penalties?
The IRS charges 0.5% of the unpaid tax for each month or partial month it stays outstanding, up to 25%. That rate drops to 0.25% during an approved installment agreement and can rise to 1% after certain unresolved levy notices.
Does the IRS charge both penalties and interest on unpaid taxes?
Yes. Penalties and interest are calculated and applied separately, which is also why this irs penalty and interest calculator only estimates the penalty side. Interest keeps accruing daily on top of whatever penalty amount is charged.
How much interest does the IRS charge on unpaid taxes?
The rate is set quarterly, based on the federal short-term rate plus 3 percentage points, and it compounds daily rather than monthly. It moves often enough that a fixed number here would go stale within a few months.
How is IRS interest on unpaid taxes calculated?
Interest is calculated daily against the outstanding balance using that quarter’s published rate, then compounds, so the amount owed grows faster the longer a balance goes unpaid. The IRS payment plan calculator factors that daily compounding into a full payoff projection if you want to see it applied.
Can IRS penalties and interest be reduced or removed?
Penalties, yes, through programs like reasonable cause relief or automatic compliance-based exemptions. Interest is much harder to remove and is generally only adjusted when it resulted from an IRS error or unreasonable delay.
Can I get an IRS penalty abatement?
Possibly. Taxpayers with a clean three-year filing and payment history often qualify automatically or through a straightforward request, while more complicated situations may need a documented reasonable-cause case. A payment plan attorney or resolution specialist can review your account and tell you which path applies before you file anything with the IRS.