Owing the IRS is stressful enough without guessing what a payment plan will cost. Our IRS payment plan calculator runs your numbers the way the IRS actually calculates them, not a rough back-of-the-napkin guess.
Enter your balance and the monthly payment you can afford, and you’ll see your estimated payoff timeline, setup fee, and total interest before you ever pick up the phone.
Whether you’re leaning toward a short-term payoff or a long-term installment agreement, the calculator uses this quarter’s real IRS fee schedule and interest rate, not numbers from a few years back.
How the Calculator Works
The tool runs on five inputs, and each one changes your result in a specific, predictable way.
The Five Inputs
- Total IRS balance: the full amount on your notice or online account, including tax, penalties, and interest already assessed
- Monthly payment you can afford: not a suggested number, just what you can realistically send
- Application method: online, or phone, mail, and in person
- Payment method: direct debit or another payment method
- Low-income status: flags whether a reduced or waived setup fee might apply
How Your Payoff Time Is Calculated
Once you calculate your IRS tax payment plan, the tool doesn't multiply your balance by a flat rate and call it done. It runs a month-by-month projection instead.
Each month, it adds that month's interest to your balance, then subtracts your payment. As your balance shrinks, so does the interest charged against it, which is closer to how the IRS actually calculates it than a single-formula shortcut.
If your payment doesn't cover even one month's interest, the calculator won't show you a payoff date at all. It'll tell you the payment needs to go up first, because the IRS would reject a plan that never actually reduces the balance.
This is still an estimate, not an IRS decision. The agency reviews and approves your actual terms, and larger balances may need extra documentation. Our payment plan attorneys can help you build an IRS installment agreement proposal the IRS is actually likely to accept.
What the Results Actually Show You
Once you hit calculate, you'll see six numbers, not just one:
- Monthly payment: the figure you entered, restated so you can double-check it against your budget
- Estimated payoff time: how many months it takes at that payment, given the current interest rate
- IRS setup fee: the one-time cost based on your application and payment method
- Estimated future interest: the total interest projected between now and payoff
- Estimated total repayment: your balance plus interest plus the setup fee
- Additional penalties: a note, not a number, since the tool can't calculate a penalty amount it doesn't have enough information to confirm
Each of those numbers moves independently depending on which input you change, so it's worth testing a couple of combinations, like a slightly higher payment or switching from mail to online, before deciding what to actually submit to the IRS.
IRS Setup Fees by Application and Payment Method
The setup fee is a one-time cost, and it's entirely within your control based on how you apply and pay.
- Online + direct debit: $22
- Online + other payment method: $69
- Phone, mail, or in person + direct debit: $107
- Phone, mail, or in person + other payment method: $178
- Low-income, direct debit: often $0, subject to IRS confirmation
- Low-income, other payment method: $43, potentially reimbursable
For your IRS monthly payment plan, that gap matters more than it looks. On a smaller balance, the difference between $22 and $178 can be a meaningful percentage of what you actually owe.
If your income falls under the IRS's low-income threshold, flag it in the calculator. A waived setup fee is confirmed by the IRS, not guaranteed by the tool, but it's worth checking before you assume you'll pay full price.
How Interest and Penalties Affect Your Estimate
Fees are a one-time hit. Interest is the part that keeps compounding while you pay.
The Interest Rate Behind the Numbers
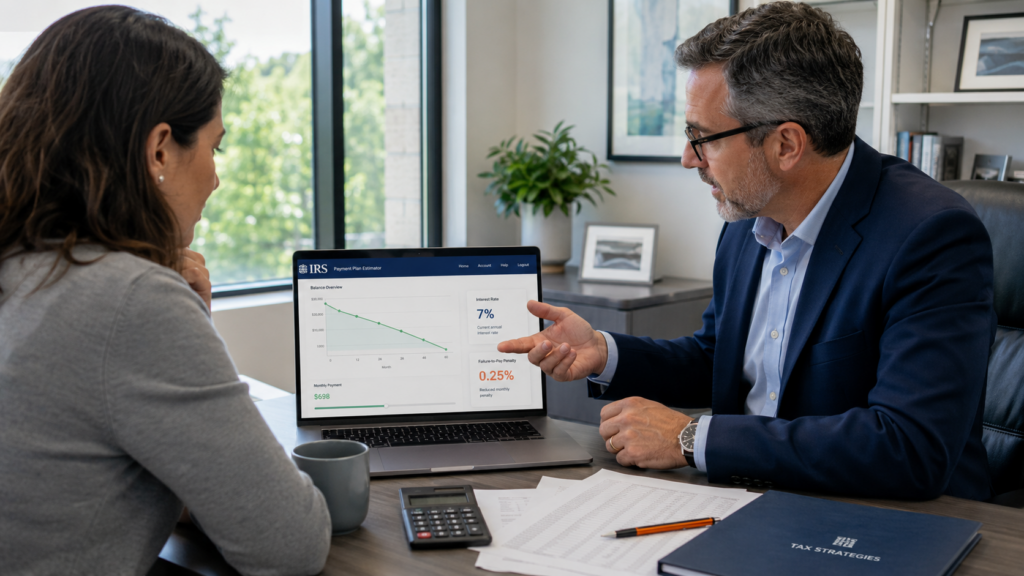
The IRS payment plan interest rate is currently 7% annually for Q4 2026 (October 1 through December 31, 2026), and the IRS reviews it every quarter. Because it compounds daily, IRS payment plan interest keeps building even after you start making payments, which is exactly why the calculator recalculates it against your shrinking balance each month instead of your original one.
Rates can move up or down at the next quarterly review, so the calculator's total is an estimate based on today's rate holding steady. See how the IRS calculates interest on installment agreements for the full breakdown.
Why Penalties Aren't Baked Into the Total
The calculator won't invent a penalty dollar figure and add it to your total. The failure-to-pay penalty depends on details it can't know from five inputs alone, like whether you filed on time, how much of your balance is unpaid tax versus prior penalties, or whether you already have an approved agreement.
What it will tell you: file on time with an approved plan, and that penalty often drops to 0.25% per month instead of the standard rate. Your actual repayment could still run higher than the estimate once penalties are factored in by the IRS.
Comparing Short-Term and Long-Term Payment Plan Estimates
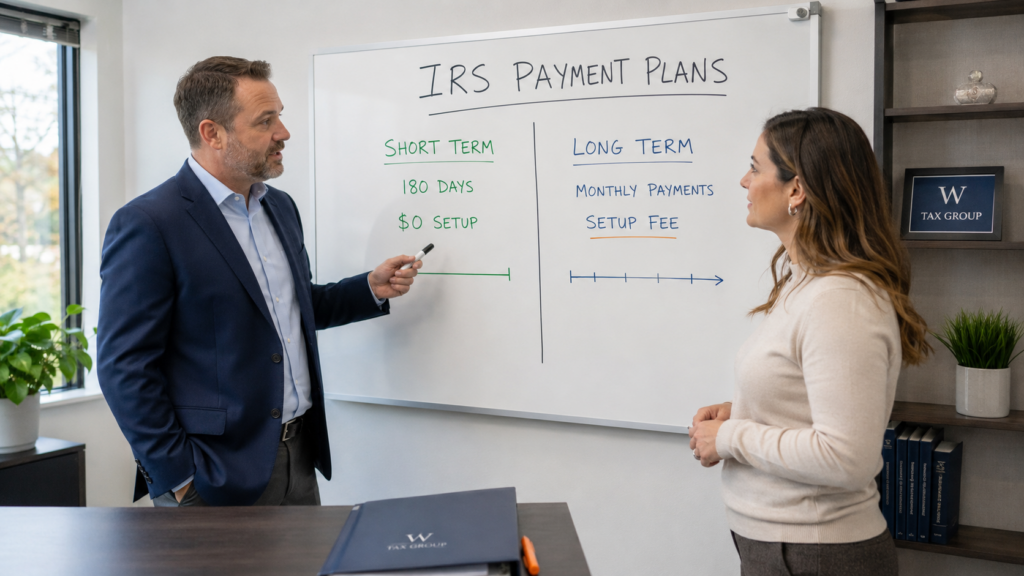
Not everyone needs years to pay the IRS off. The calculator runs a second estimate alongside your main one, a 180-day payoff, so you can compare both before deciding.
The Short-Term Estimate
An IRS short-term payment plan skips the setup fee entirely and assumes you'll clear the balance within six months:
- Up to 180 days to pay in full
- $0 IRS setup fee
- Individuals owing under $100,000 combined can typically apply online
The Long-Term Estimate
An IRS long-term payment plan is the calculator's main projection. It spreads your balance across as many months as your payment amount requires, based on the balance, application method, payment method, and low-income status you entered.
Balances of $50,000 or less, with all returns filed, often qualify for a Simple Payment Plan with minimal documentation. Above that threshold, the calculator will note that you may need a full financial statement under a non-streamlined installment agreement instead.
When the Calculator Flags Your Plan
Two warnings show up automatically, and both are worth taking seriously:
- Payoff stretching past 120 months: your selected payment may exceed a typical ten-year collection window, and actual terms depend on the IRS's remaining time to collect your specific debt.
- Payment too low to reduce your balance: the calculator won't display a payoff date, because that payment wouldn't actually work.
If you land in between, more than the short-term minimum but not the full balance in six months, a partial payment installment agreement may fit better than either estimate on its own.
Know What You Owe Before You Apply
Most taxpayers call the IRS and hope for the best. The ones who get a plan that actually fits usually run the numbers first, so there are no surprises once it's approved.
Use the calculator above to see your real payoff time, setup fee, and interest, then decide which application and payment method saves you the most.
Some situations go beyond five inputs, like unfiled returns, prior penalties, or an active revenue officer. In those cases, The W Tax Group can review your file and negotiate directly with the IRS on your behalf.
Frequently Asked Questions
How is an IRS payment plan monthly payment calculated?
There's no fixed formula. It's based on what you can reasonably afford after income and necessary expenses. For larger balances, the IRS may request a financial statement like Form 433-F before approving it.
Does IRS installment plan interest change over time?
Yes. The interest rate on your IRS payment plan is set quarterly, based on the federal short-term rate plus 3%, so it can move every few months. It also compounds daily.
Does the IRS charge penalties while you are on a payment plan?
Usually, yes, but at a reduced rate. File on time with an approved agreement, and the failure-to-pay penalty typically drops to 0.25% per month.
What is the difference between an IRS short-term and long-term payment plan?
A short-term plan gives you up to 180 days with no setup fee. A long-term installment agreement spreads payments over months or years and carries a setup fee based on how you apply and pay.
How long can I take to pay the IRS?
It depends on your balance and the IRS's remaining collection window, but many taxpayers get several years to pay under a long-term plan. The IRS sets the exact terms.
Can I pay off my IRS payment plan early?
Yes, with no prepayment penalty. Paying extra or paying off early reduces the total penalty and interest on your IRS payment plan that would otherwise keep accruing.
Does an IRS payment plan stop penalties and interest?
No, but it can reduce them. Interest keeps accruing, and while the failure-to-pay penalty may drop to 0.25% monthly, both continue until the balance is paid off. Missing a payment can also put your agreement into default.